AGL said no to an $5 billion bid, but it isn't over – here's how takeover bids work
- Written by: Ian Ramsay, Emeritus Professor, Melbourne Law School, The University of Melbourne
Australian companies are being taken over like never before. On Saturday February 19 a consortium involving tech billionaire Mike Cannon-Brookes and Canadian asset manager Brookfield offered A$5 billion[1] to buy AGL Energy.
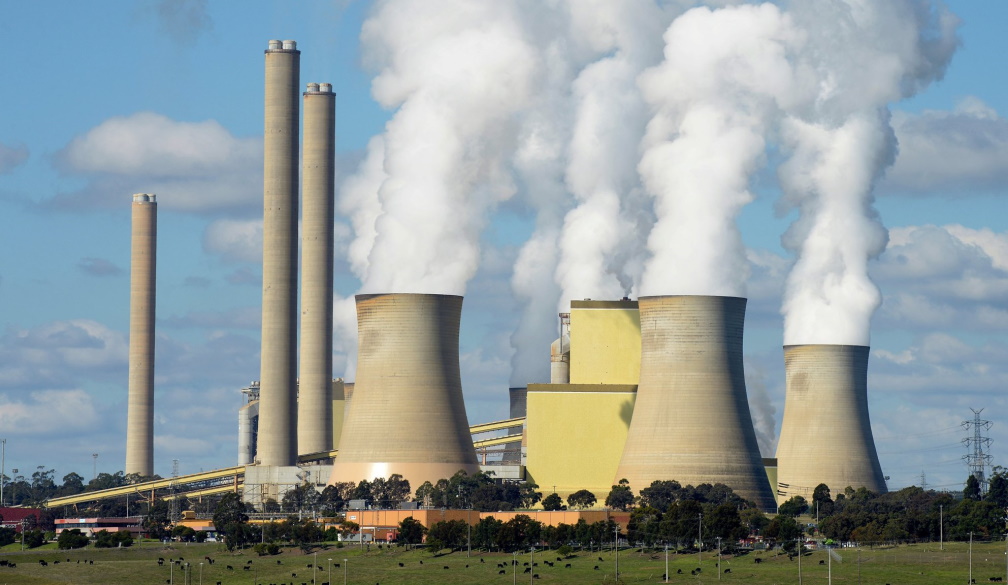
AGL is Australia’s biggest[2] electricity supplier and owns Australia’s two highest emitting[3] power stations.
The bidders plan to shut down[4] those coal-fired plants early and invest up to $20 billion in clean energy and storage to replace them.
On Monday February 21, AGL announced[5] that it had rejected the offer because it “materially undervalues the company on a change of control basis and is not in the best interests of AGL Energy shareholders”.
The offer price was 4.7% above the price of AGL shares the day before the offer, something the AGL chief executive called a “ridiculously low premium[6]”.
Even though much of Australia was locked down throughout much of 2021, the Financial Times says last year was a record year[7] for Australian takeovers, with $308 billion of deals struck compared to a 10 year average of $100 billion.
Among the deals were $23.6 billion for Sydney Airport[8] and $39 billion for Afterpay[9]. The pace has continued in 2022 with Crown Resorts[10] accepting $8.9 billion from Blackstone Inc.
There are two main types of takeovers
Increasingly, takeovers have been undertaken as schemes of arrangement. Each of the big takeovers mentioned - for AGL, Sydney Airport, Afterpay and Crown Resorts - has been a scheme of arrangement.
How takeover bids work
No one is permitted to acquire more than 20% of a company’s voting shares unless they acquire them in a way authorised by the Corporations Act. These authorised ways include a takeover bid, a scheme of arrangement and “creeping” acquisitions, whereby shareholders can increase their stake by 3% each six months.
The prohibition is broader than just acquiring voting shares and includes situations where, for example, a person may not actually own shares but they control the voting rights attached to the shares. The intention is to not allow someone to hide their control of a company.
Read more: What impacts do takeover defences have on shareholders?[11]
The provisions apply to companies listed on the securities exchange, unlisted companies with more than 50 shareholders, and listed registered managed investment schemes.
In takeover bids, the bidder is required to make an offer to each shareholder.
Each shareholder gets information about the offer and decides whether to accept or reject it. A shareholder who does not accept will usually only be forced to give up their shares if the bidder gets enough acceptances to reach 90% and triggers the compulsory acquisition provisions in the Corporations Act.
How schemes of arrangement work
A scheme of arrangement requires a meeting of the company’s shareholders to vote on whether to accept the scheme. This is not the case for a takeover bid.
As in a takeover bid, the shareholders are given information on the offer beforehand.
Even the shareholders who oppose the scheme have to give up their shares should the scheme be approved by the company’s shareholders and the court.
The required majorities in favour are:
In addition, the scheme of arrangement requires court approval to ensure all shareholders are treated fairly. Court approval is not required for a takeover bid.
Why schemes are becoming more popular
Among the reasons why schemes of arrangement have grown in popularity compared with takeover bids are
-
if the scheme is approved by the required majorities of shareholders and the court, 100% ownership of the target company is obtained, even if some shareholders vote against the scheme
-
the voting majorities required are lower than the 90% of shares required to undertake compulsory acquisition following a takeover bid
-
a scheme can have more flexibility in its structure to make the offer more attractive to shareholders.
A key issue for a bidder when choosing between a scheme and a takeover bid is a scheme requires the approval of the board of directors of the target company to put the proposal before shareholders, whereas a takeover bid does not.
This means that a scheme cannot be used for a hostile takeover (one not supported by the target company’s board). In contrast, a takeover bid can be either friendly or hostile.
What’s next for AGL?
The proposed takeover of AGL is structured as a scheme and has been rejected by the AGL board because the price was too low.
Brookfield and Cannon-Brookes might return with a higher bid, which might gain the board’s support and be presented to shareholders.
If that happens, it won’t be the end. The scheme would need to be approved by shareholders and the court. Also, the approval of both the Australian Competition and Consumer Commission and the Foreign Investment Review Board is needed.
Read more: The battle for AGL heralds a new dawn for Australian electricity[12]
If the board continues to oppose the offer and to oppose any higher offer, the bidders could restructure their proposal as a hostile takeover bid, requiring only sufficient shareholder acceptance and approval from the regulators.
And there might be another bidder for AGL. Mike Cannon-Brookes said on Thursday he was playing “chess not chequers[13]”, suggesting we are only in Act One.
References
- ^ A$5 billion (bep.brookfield.com)
- ^ biggest (theconversation.com)
- ^ emitting (www.cleanenergyregulator.gov.au)
- ^ shut down (bep.brookfield.com)
- ^ announced (www.agl.com.au)
- ^ ridiculously low premium (www.afr.com)
- ^ record year (www.ft.com)
- ^ Sydney Airport (assets.ctfassets.net)
- ^ Afterpay (www.afr.com)
- ^ Crown Resorts (www.theguardian.com)
- ^ What impacts do takeover defences have on shareholders? (theconversation.com)
- ^ The battle for AGL heralds a new dawn for Australian electricity (theconversation.com)
- ^ chess not chequers (reneweconomy.com.au)