Who can afford to build Australia’s next homes?
- Written by: The Times
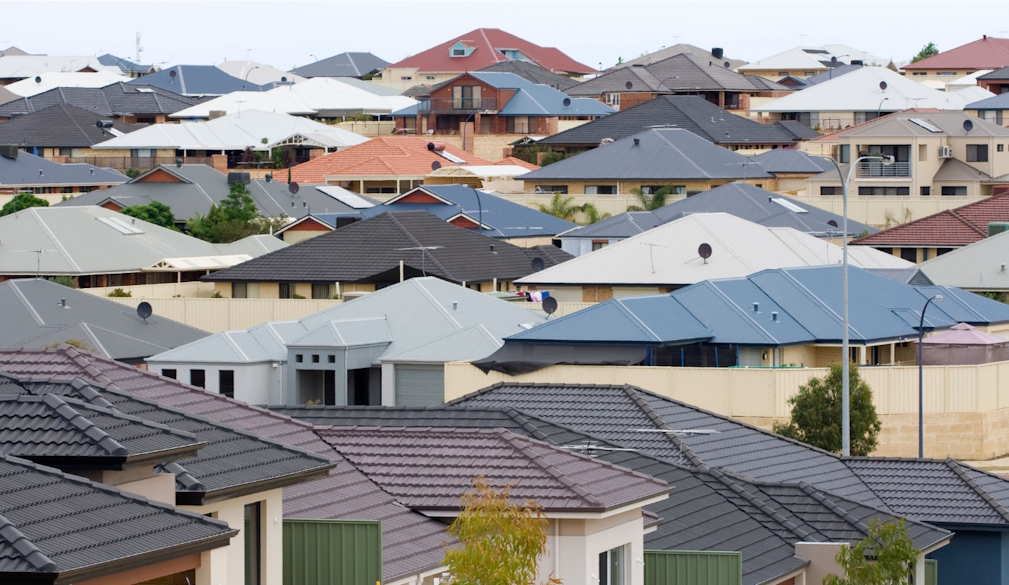
The familiar dream of buying a block, choosing a design and hiring a builder is becoming harder for first-home buyers to achieve. Australia is still building houses—but delivering homes at prices ordinary households can afford is a different challenge.
For generations, the ambition was straightforward.
A couple would save a deposit, buy a modest block of land, choose a house they could afford and engage a builder. The garden, landscaping and perhaps another bedroom could come later.
It was a pathway into ownership built around starting small.
That pathway still exists, particularly in some outer suburban and regional markets. But describing it as an ordinary, readily achievable first step increasingly overlooks the financial commitment and risk involved.
Before a young household has somewhere to live, it may need to finance land, construction, site preparation, approvals and the cost of living elsewhere while the house takes shape.
The question is no longer simply whether Australians want new homes.
It is who can afford to commission them—and who can afford to build them for the price buyers can pay.
Houses are still being built
There is an important distinction between a difficult housing market and a construction industry that has stopped.
The latest Australian Bureau of Statistics figures show work began on 52,201 dwellings in the June quarter of 2026, up 7 per cent from the previous quarter in seasonally adjusted terms.
Private sector detached house commencements rose 11.6 per cent to 31,707. Other private residential commencements, including apartments and townhouses, were essentially unchanged at 19,126. Detached housing remains a substantial part of new construction.
Those figures do not, however, tell us that an average first-home-buying couple can comfortably afford a block and a new house.
Construction activity measures what is being built. Affordability determines who gets to own it.
A house commissioned by an established owner using substantial equity counts towards supply just as a modest first home does. Yet the financial circumstances behind those two projects can be very different.
Who actually builds a home?
“Developers” and “builders” are often treated as interchangeable descriptions. They perform different functions, although some businesses undertake both.
A land developer typically assembles land, secures approvals and arranges subdivision and infrastructure before selling individual lots.
A home builder constructs the dwelling. Its customer might be a first-home buyer, an investor, an established homeowner or a development company.
An apartment developer generally brings together the site, design, approvals, finance and sales arrangements, then engages a construction company to deliver the building.
There are also community housing providers, government housing agencies and institutional rental investors commissioning homes.
The distinction matters because a couple buying in a new estate may already depend on a developer to produce the block, even when they separately choose their builder.
Australia’s traditional home-building dream has always required an industry behind it. The pressure now is on whether that industry can deliver a finished product within an ordinary household’s borrowing capacity.
The price of the block is only the beginning
A vacant block can appear to offer a cheaper entry into ownership.
But land is only one component of the finished home.
Depending on the site and contract, buyers may also face excavation, retaining walls, soil-related foundation requirements, drainage, utility connections, driveways, fencing and other expenses beyond the advertised base house price.
Some costs can be controlled by choosing a smaller home or simpler finishes. Others arise from the land itself.
During construction, households may also be paying rent while meeting interest costs on money progressively drawn down for the build.
A delay therefore has a household consequence as well as a construction consequence.
For a buyer with substantial savings, an unexpected expense may be manageable. For a couple already borrowing near their limit, the same expense can undermine the project.
The danger is that a home appears affordable when its components are considered separately, but becomes unaffordable when the complete cost is assembled.
Building costs have changed the equation
The National Housing Supply and Affordability Council reported in August that house construction costs rose 2 per cent in the June quarter and were 51 per cent above their level before the pandemic and associated supply disruptions.
It also warned that higher construction costs could make some projects financially unviable, while interest rate increases and softer sentiment could defer construction.
That creates pressure on both sides of the contract.
Buyers need a price they can finance. Builders need a price that covers labour, materials, overheads and the risks of completing the work.
A builder accepting an inadequate price does not create lasting affordability. It creates the possibility of financial distress before the home is finished.
Equally, a commercially sustainable building price may simply exceed what a first-home buyer can borrow.
Between those two limits sits a growing policy problem: a home can be needed, approved and physically possible to build, yet still fail to proceed.
Why apartments are not automatically cheap
Apartments can spread the cost of expensive land across more households. They also allow more people to live near employment, public transport and established services.
But a smaller dwelling does not automatically mean inexpensive construction.
Apartment projects can require substantial structural work, lifts, fire protection, shared services, professional design and lengthy financing arrangements. Developers must assemble enough revenue to cover the entire project before it becomes commercially viable.
Where lenders require presales, buyers must also commit before construction is complete.
This helps explain an uncomfortable possibility: a community can urgently need moderately priced apartments while a proposed development only becomes viable at substantially higher selling prices.
The need for housing does not, by itself, close that financial gap.
Nor does approving a tower guarantee that it will become a building.
Wealth buys more room to move
An established owner with substantial equity approaches the market differently from a household saving its first deposit.
That owner may be able to renovate, extend, buy a prestige property or replace an existing house. There may be room to absorb a variation, delay or higher quote.
A first-home buyer often has much less flexibility.
This does not establish that every prestige market is thriving or that every affordable market is falling. Local conditions differ, and a weak entry-level market can mean fewer transactions or stalled projects rather than lower prices.
But it explains why expensive renovations and premium developments can remain visible while households further down the income scale struggle to get a project started.
The ability to improve an existing home and the ability to acquire a first home are becoming increasingly separate financial experiences.
There is another distinction: renovating a large house may improve its quality without increasing the number of homes available.
Construction expenditure and additional housing supply are not the same thing.
Developers cannot sell below cost indefinitely
Developers are central to housing supply, but relying on private development also means recognising how projects are selected.
A project generally needs a credible return after land, construction, finance, infrastructure, professional fees, selling expenses and risk.
If those costs exceed what prospective buyers can pay, the project may be redesigned, delayed or abandoned.
That is why rising housing need can coexist with stalled development.
It is also why simply demanding that developers build cheaper homes is insufficient. The underlying cost of delivering those homes must fall, or another funding model must help bridge the gap.
Competition, scrutiny and consumer protection remain necessary. So does a realistic understanding of project economics.
Restoring a modest starting point
Australia needs more than one route into housing.
Detached houses remain important, particularly for families and in locations where land and infrastructure make them practical. Apartments, townhouses and smaller dwellings can provide alternatives where a conventional block is too expensive.
The Productivity Commission’s interim housing supply report identifies land-use reform and better coordination of infrastructure as major opportunities to improve supply and affordability. It also warns that poorly coordinated roads, utilities and sewerage can leave rezoned land unavailable for housing for years.
The practical task is to make more modest homes possible in places where people can reasonably live and work.
That means serviced land, predictable approvals, viable construction businesses and housing designs that use space efficiently. It also means social and affordable housing for people whose needs cannot be met by ordinary commercial development.
A smaller purchase price on the fringe is not a complete solution if the household must absorb excessive transport costs and inadequate services.
Affordability has to survive occupation, not merely settlement.
The Times View
It would be premature to declare the couple buying a block and building their first home a thing of the past.
But it would be equally misleading to present that pathway as readily available to everyone willing to work and save.
Australia still has builders, developers and households commissioning homes. What it increasingly struggles to provide is a workable meeting point between the cost of construction and the purchasing power of people entering the market.
The answer cannot depend entirely on young buyers borrowing more, parents contributing more or households accepting ever greater financial risk.
Nor should success be measured only by the value of building work or the number of expensive properties changing hands.
A housing system should be judged by whether people can afford to begin—not only by what the wealthy can afford to improve.