Why the RBA shouldn't obsess over inflation when it sets interest rates
- Written by: John Quiggin, Professor, School of Economics, The University of Queensland
Later today, everyone expects the Reserve Bank board will push up its cash interest rate for the second consecutive month.
Why? According to the board’s official minutes[1], it’s:
to ensure that inflation in Australia returns to the target over time
Some increase in interest rates is justified simply because with higher inflation, real interest rates are now negative. But the idea of returning to the old target range does not stand up to scrutiny.
Once the current spike in inflation is over, we need to reconsider both the target range and the whole idea of inflation targeting.
How much inflation are we aiming for now?
The Reserve Bank’s inflation target is consumer price inflation of 2-3%[2], on average, over time.
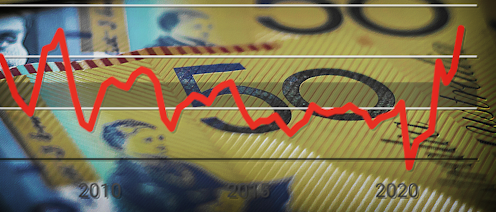
Yet for most of the past ten years that target has been missed, on the downside, as you can see below.
But, just recently, consumer price inflation has jumped to 5.1%, and the so-called “trimmed mean[3]” measure of underlying inflation watched closely by the bank has jumped to 3.7%.
Recent inflation is partly a sign of success
While too much inflation can be a problem, it is important to remember that the jump is partly an unintended consequence of success.
Massive public spending offset the impact of COVID and lockdowns on household outcome, and set the stage for a rapid economic recovery.
This spending was necessary, but inevitably went to businesses that didn’t need it.
Further, the success of working from home meant many households suffered no reduction in income and were freed of the need to spend as much on travel and clothes, and things such as makeup that go with travelling to work.
Read more: At 3.9%, Australia's unemployment rate now officially begins with '3'[4]
As restrictions have eased, households and businesses have been keen to spend some of their accumulated savings, at a time when goods production has been disrupted, especially by the anti-COVID measures in China.
The result has been classic inflation[5] of the kind where “too much money chases too few goods”.
It is very different from Australia’s last major episode of inflation, in the 1960s and 1970s, which was commonly seen as a “wage-price spiral[6]” or “cost-push inflation[7]”.
This isn’t wage-driven inflation
Cost-push inflation was generally seen as arising when powerful unions demanded large wage rises, which were passed on to consumers by corporations with monopoly power.
In the current environment, while monopoly power is still a problem, unions are a shadow of their former selves, with little power to extract out-sized increases.
The result is that wages, as measured by the Bureau of Statistics wage price index, grew by only 2.4%[8] in the year to March, well behind inflation of 5.1%[9].
This has continued a long downward trend in the wage share of national income.
Despite the obvious absence of wage-push, many commentators are still working on the wage-price spiral model, and arguing against[10] allowing wages to rise in line with inflation.
Such a policy would not only be unfair, it would be economically disastrous – similar to the austerity policies[11] introduced in many countries in the wake of the global financial crisis, and earlier, when Britain returned to the gold standard in the wake of World War I, helping precipitate and deepen the great depression[12].
In the current context, real wage cuts brought about by less than full compensation for inflation would lead workers to quit and seek new jobs, worsening labour shortages.
Read more: National income is climbing, but the share going to wages is shrinking[13]
It is striking that many of the same employer representatives who are saying wage increases are unaffordable[14] are also complaining it’s hard to find workers[15].
The correct response to the huge expansion in the amount of money in the economy during the crisis is to accept a once-off increase in prices and wages, as well as incomes indexed to wages and prices, such as pensions.
For now, prices should flow through into wages
This would share the real costs of the pandemic spending more evenly across the community than if wage-earners were expected to bear the burden.
Later, we can return to the use of monetary policy, based on adjustments in the Reserve Bank cash rate, to maintain inflation at an acceptable level. But what should that level be?
For the past 30 years or so, the RBA has targeted an inflation rate of 2-3%, but the rationale for a rate that low was always weak, and has since broken down.
Read more: Proof positive. Real wages are shrinking, these figures put it beyond doubt[16]
In the 1990s, the main argument for a low target rate of inflation was the need to break expectations created by decades of high inflation.
By contrast, the current inflationary episode is more like the brief inflationary bursts of the 1950s, which vanished once the drivers of inflation were removed.
Even during the heyday of inflation targeting, critics argued that low inflation in goods and services prices contributed to asset price instability[17], potentially giving rise to financial crises.
Many, including myself[18], have long preferred an inflation target of 4%[19]. Now there’s a new argument for it.
In time, we will need a new target
A central concept in monetary policy is the neutral real rate of interest[20]: that is, the interest rate adjusted for inflation at which monetary policy is neither expansionary nor contractionary.
Over the past twenty years the neutral real rate is believed to have fallen to close to zero[21], or possibly even less, meaning that if inflation is 2-3%, the neutral actual rate should be 2-3%.
But the nail is hard to hit. Actual rates of interest set by central banks tend to vary around the neutral rate, by as much as three percentage points either way.
Read more: Open letter: the RBA review should be independent of government[22]
This raises the prospect of the target cash rate going negative, and interest rates can’t usually go far below zero. We’ve seen this “zero lower bound” operating in Australia and elsewhere for years now.
So, if we are to continue with inflation targeting, and get it right, it will be necessary to raise the 2-3% inflation target.
Given the obvious political difficulties of doing this, it may be better to abandon inflation targeting altogether, as suggested for some time by myself[23] and economists backed by former Senator Nick Zenophon[24].
It’s one of a number of ideas likely to be put to the independent review[25] of the Reserve Bank promised by Treasurer Jim Chalmers during the election.
References
- ^ official minutes (www.rba.gov.au)
- ^ 2-3% (www.rba.gov.au)
- ^ trimmed mean (www.rba.gov.au)
- ^ At 3.9%, Australia's unemployment rate now officially begins with '3' (theconversation.com)
- ^ classic inflation (www.investopedia.com)
- ^ wage-price spiral (www.economicshelp.org)
- ^ cost-push inflation (www.investopedia.com)
- ^ 2.4% (www.abs.gov.au)
- ^ 5.1% (www.abs.gov.au)
- ^ arguing against (www.theaustralian.com.au)
- ^ austerity policies (www.businessinsider.com)
- ^ precipitate and deepen the great depression (www.taylorfrancis.com)
- ^ National income is climbing, but the share going to wages is shrinking (theconversation.com)
- ^ unaffordable (www.theaustralian.com.au)
- ^ hard to find workers (www.australianchamber.com.au)
- ^ Proof positive. Real wages are shrinking, these figures put it beyond doubt (theconversation.com)
- ^ contributed to asset price instability (www.semanticscholar.org)
- ^ including myself (johnquigginblog.substack.com)
- ^ 4% (www.imf.org)
- ^ neutral real rate of interest (www.brookings.edu)
- ^ close to zero (www.ampcapital.com)
- ^ Open letter: the RBA review should be independent of government (theconversation.com)
- ^ myself (www.afr.com)
- ^ Nick Zenophon (theconversation.com)
- ^ independent review (theconversation.com)