How and where we build needs to change in the face of more extreme weather – the insurance industry can help
- Written by: Michael Naylor, Senior Lecturer in Economics, Massey University
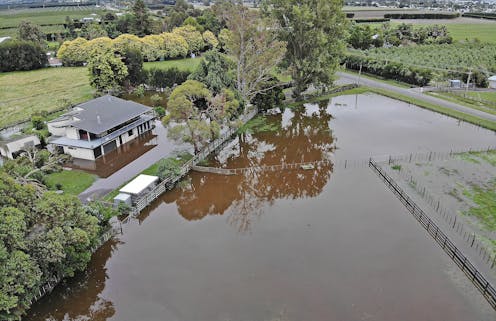
As New Zealand considers how to better prepare for a future affected by climate change, the insurance sector needs to be part the discussion on where and how we build our homes.
This involvement should include input into future building standards. Insurers should also play a key role in deciding which areas of New Zealand are removed from residential use – aka red-zoned – and when this red-zoning should occur.
If insurers are not involved in the discussions on how the country adapts to climate change, we risk whole sections of the country becoming uninsurable.
Frequent disasters make homes uninsurable
It is clear the risk of damage from climate change has increased in recent years. In late January and early February, large swathes of the North Island were hit by damaging weather systems that left 750 homes red stickered[1] – meaning entry to the property was prohibited. Thousands more need significant repair.
Over the past few years, insurers have responded to the increasing risks by raising premiums in general or suggesting that clients at more risk increase their excesses. Insurers have also begun to charge premiums based on individual property risk[2].
As the threat of natural disaster increases, insurers will have no choice but to raise some clients’ premiums to unaffordable levels or withdrew the offer of insurance all together.
Read more: Landslides and law: Cyclone Gabrielle raises serious questions about where we've been allowed to build[3]
The general rule of thumb is that any event which occurs once every 30 years will make a property uninsurable. Some areas of New Zealand, like the East Coast or Edgecumbe, are well past that in terms of the frequency of natural disasters. Cover in these areas is only provided as a public relations gesture.
But as the risk of a significant event increases, the companies that guarantee retail insurers for the most extreme events – known in the business as reinsurers – could force the withdrawal of all cover in some areas. These reinsurers could decide that some parts of New Zealand are simply too risky.
A threat to home ownership
This decision to pull out of certain areas will have a negative effect on home ownership. Banks routinely require a house to be insurable before considering a mortgage[4]. Banks also consider whether a house will be insured for the entire length of the home loan.
The difficulty here is that areas which are currently low risk could become high risk in the future thanks to climate change. This rising risk is likely to lead to a situation where insurers will be forced to withdraw cover from clients who still have decades left on their mortgages.
Alternatively, if a property is currently insured but is likely to become uninsurable during the lifetime of a mortgage, banks may become very conservative in issuing home loans to areas they consider risky.
An additional problem is that council consents for housing have been based on statistics of past climate events – set at a one-in-a-hundred or one-in-two-hundred year level. As we have recently seen, climate change makes these statistics dubious.
Instead, consents need to be based on multiple scenarios, given the various potential climate futures. New Zealand needs to determine clearly which areas are likely to be affected and plan ahead.
A role for insurers
The best path forward would be to establish a multi-disciplinary expert group that includes members of the insurance industry and reinsurers, to create a set of criteria and scenarios for housing development.
This group could set the guidelines councils use to determine if a rural area should be opened to new housing development, for example, or if an existing housing area should be red-zoned, with houses removed at a definite future date.
By including insurers, new building standards could be set so that homes better withstand climate change, improving the likelihood of them being insured.
Read more: With seas rising and storms surging, who will pay for New Zealand’s most vulnerable coastal properties?[5]
Insurers could then be required to use the mutually agreed criteria to set risk-based premiums. If all insurers use the same criteria, then competition would be based on price and service, and not hidden risk models.
The risk models which insurers create, based on those criteria and the climate scenarios, could be open to public debate. The pricing attached to the risk factors could be flexible as climate change makes some areas higher risk.
A dynamic understanding of risk
In the end, red-zoning needs to be seen as dynamic rather than static. There needs to be the option to withdraw insurance coverage in the future, based on evolving models of climate change risk. And all potential risks need to be clearly communicated to potential buyers though land information memorandum (LIM[6]) reports.
Read more: Climate change is already putting the heat on insurance companies – Auckland's floods could be a turning point[7]
Taking this collaborative and transparent approach would mean insurers could be required to guarantee an offer of insurance renewal for a fixed number of years, allowing buyers to match the length of their insurance to their mortgage term.
The role of EQC[8] or the reinsurers would be to back these fixed-term insurance policies in the case of significant disasters.
Working with the insurance industry would offer a level of certainty as we face an uncertain future – helping New Zealanders protect their homes in the face of changing risks.
References
- ^ 750 homes red stickered (www.nzherald.co.nz)
- ^ individual property risk (anziif.com)
- ^ Landslides and law: Cyclone Gabrielle raises serious questions about where we've been allowed to build (theconversation.com)
- ^ insurable before considering a mortgage (www.settled.govt.nz)
- ^ With seas rising and storms surging, who will pay for New Zealand’s most vulnerable coastal properties? (theconversation.com)
- ^ LIM (www.settled.govt.nz)
- ^ Climate change is already putting the heat on insurance companies – Auckland's floods could be a turning point (theconversation.com)
- ^ EQC (www.eqc.govt.nz)