5 Best Online SMSF Setup Services in Australia: Fixed Fee or Quote on Request
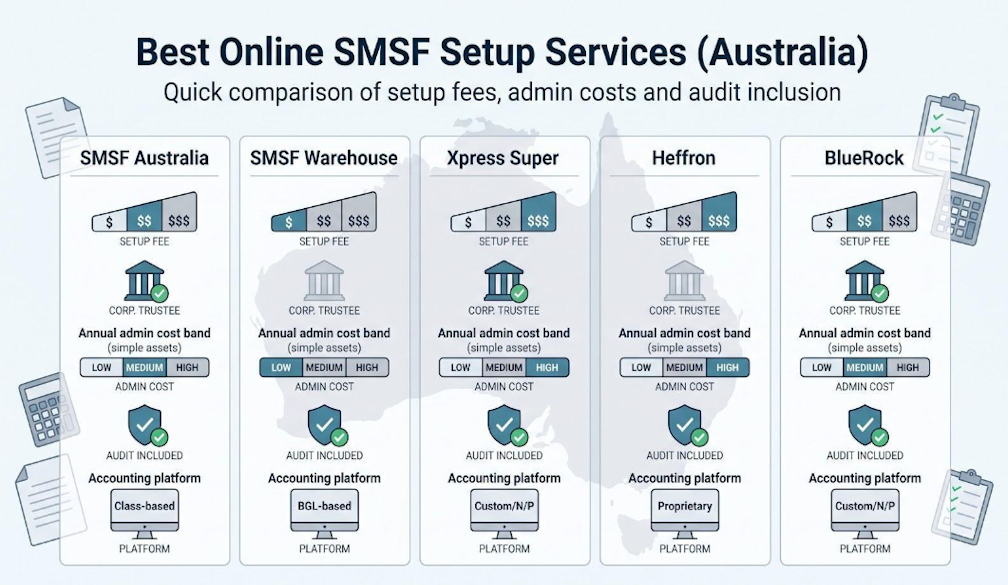
Running your own self-managed super fund (SMSF) is more popular than ever: more than 672,000 funds now control about $1.06 trillion in retirement savings. In this guide, we compare five online SMSF setup services that handle the trust deed, a corporate-trustee company, ATO registration, and ongoing compliance for a fixed - or clearly quoted - price. All figures are in Australian dollars and were verified on August 5 2026, after ASIC lifted its company-registration fee to $636 on July 1. The information here is general; get personalised tax, legal, or financial advice before acting.
Quick answer: how the five online SMSF setup services stack up
Below is the at-a-glance fee matrix many readers ask for. Amounts are in Australian dollars and were verified on August 5 2026. ASIC raised the company-registration fee to $636 on July 1; any provider still listing $611 is out of date.
The five services compared below run from $1,300 + GST a year at the simple end to more than $3,900 for complex funds once compulsory accounting and the independent audit are counted, so a “free setup” banner rarely reflects the real bill.
|
Provider |
Category pick |
Setup fee (corporate trustee)† |
Corporate trustee bundled? |
Annual admin (simple assets) |
Independent audit included? |
Accounting platform |
|
SMSF Australia |
Integrated legal + accounting support |
$2,000 + GST (includes $636 ASIC) |
Yes |
From $1,300 + GST |
Yes |
Class Super |
|
SMSF Warehouse |
Most detailed public fee list |
$1,400 incl. GST |
Yes |
$1,320 incl. GST (Advanced plan) |
Yes |
Simple Fund 360 (optional login $30 / mth) |
|
Xpress Super |
Bundled bank + broker onboarding |
Fund $700 + company $1,005 |
No |
$1,925 (GST to confirm) |
Yes |
N/P |
|
Heffron |
Complex-asset specialists |
Fund $550 + company $1,007 |
No |
From $3,195 incl. GST |
Yes |
Proprietary portal |
|
BlueRock |
Clear LRBA and structure pricing |
$2,750 incl. GST |
Yes |
Quote required |
N/P |
N/P |
†Figures include the current $636 ASIC registration where stated.
Treat these totals as a starting point, not the full bill. Property, crypto, pensions, and GST reporting increase costs, and some firms price every extra line item separately. The next sections unpack those nuances so you know exactly what you’ll pay, and what service you’ll get, over the first three years of running your fund.
What we mean by an online SMSF setup service
An online SMSF setup service moves you from a blank page to a fully registered, legally compliant self-managed super fund without printing or posting a single form.
The minimum scope we include
-
Legal documents, a lawyer-drafted trust deed plus a special-purpose company constitution (if you choose a corporate trustee).
-
Government registrations, electronic lodgement of the company with ASIC, ABN, and TFN applications, and the ATO “regulated fund” election.
-
Connectivity, creation of a SuperStream electronic service address and a step-by-step bank-account guide so employer and rollover money can land in the fund, following the ATO’s guidance on setting up a bank account.
-
Starter paperwork, help to roll your existing super accounts across and an investment-strategy template that satisfies the ATO’s current guidance on starting an SMSF.
-
Ongoing compliance, a bundle (or clearly organised add-on) covering annual accounts, the SMSF tax return, and an independent audit, because the ATO makes all three compulsory each year.
Because those moving parts create costs every year, we compare three-year totals rather than headline setup fees alone.
What an online SMSF setup really costs
1. One-off costs most trustees miss
A low headline figure can hide several compulsory start-up charges:
- ASIC company registration, $636 from July 1 2026 (up from $611 the year before). Every corporate trustee pays this special-purpose company fee, even when the ad shouts “free setup.”
- Lawyer-drafted trust deed. Often bundled, but ask who maintains it and what future updates will cost you.
- Government paperwork. ABN, TFN, and the ATO “regulated fund” election carry no government fee, yet someone must prepare them accurately.
- Extras such as a registered office, SuperStream electronic service address, and director IDs. Some firms bundle these, others price them individually.
Add everything together and a realistic single-hit bill usually lands between $1,400 and $2,800, even when the banner reads “$0 upfront.”
2. Ongoing costs you will see every year
Annual fees matter more than the flashy launch price:
- ATO supervisory levy, $518 in year one (billed a year in advance), then $259 a year after that.
- ASIC annual review, $70 for a special-purpose company (effective the same day the registration fee rose).
- Core administration (bookkeeping, tax return, and an independent audit) ranges from about $1,300 to $3,000 for a plain share-and-ETF portfolio. Property, crypto, pensions, or quarterly BAS quickly add hundreds more.
- Technology licences. A Class or Simple Fund 360 subscription may be included or appear as roughly $30 a month.
- Specialist extras. Actuarial certificates for pension accounts, title searches for property, and wallet-reconciliation fees for crypto can double the “cheap” option.
In practice, budget at least $1,800 to $2,500 a year for a vanilla fund. If you own a warehouse or trade digital assets, expect the number to climb, so ask for a full rate card before you sign.
How we chose the five providers on this list
Our research began with a spreadsheet of 32 businesses that advertise online SMSF setup services.
Step 1, eligibility screen
A brand stayed on the sheet only if it published:
- a clear setup price,
- a corporate-trustee option, and
- the name of the firm that performs the annual independent audit.
Sites still quoting the pre-2026 ASIC company-registration fee of $611 after it rose to $636 on July 1 2026 failed instantly.
Step 2, assessment criteria
|
Factor |
What we looked at |
|
Compliance & document quality |
Deed provenance, ATO registrations, independent audit |
|
Three-year total cost |
Setup, admin, statutory fees |
|
Fee transparency |
GST flags, full rate card, no hidden extras |
|
Human support |
Published response times, escalation path |
|
Technology integration |
Named software, data feeds, portability |
|
Independent reputation |
Review data across Google and ProductReview |
|
Onboarding speed |
Document turnaround, full “ready to invest” timeline |
A stale statutory fee or a missing GST tag counted heavily against a provider.
Step 3, conflict check
We may earn referral income from some, but not all, providers. Commercial links did not override these criteria. Any partner that fell short on them was excluded.
After all three gates, five names remained: SMSF Australia, SMSF Warehouse, Xpress Super, Heffron, and BlueRock. Each excels in a different niche - integrated legal work, granular fee tables, bundled banking, complex-asset capability, or clear LRBA pricing - so you can match the service to your investment style instead of chasing a single “best overall” trophy.
All data was captured on August 5 2026 from published pricing, ASIC and ATO records, and written provider responses. We will update this guide when ASIC fees change again or a provider revises its price list.
SMSF Australia: Best for integrated SMSF legal and accounting support
SMSF Australia Online SMSF Setup Service Homepage Screenshot
SMSF Australia charges a flat $2,000 + GST to establish a fund, and it is genuinely flat. That single fee covers the $636 ASIC company registration charge for the corporate trustee, lawyer-drafted deed and constitution, ATO registrations, rollovers from your existing funds, bank-account assistance, and registered office and electronic service address services for the first 12 months. You can learn more about what the fee includes before you commit, which is the point: no hidden extras surface later.
Source: provider fee schedule captured 5 August 2026.
Why we picked it
SMSF Australia is one of the few online setups with in-house SMSF lawyers and certified SMSF accountants. That single-team model means your deed changes, property add-ins, or compliance fixes don’t bounce between contractors.
Pricing clarity
- Setup, $2,000 + GST, including the current $636 ASIC company fee and a lawyer-drafted deed.
- Annual administration, a basic listed-asset portfolio starts from $1,300 + GST; property or crypto places the fund in the complex tier. You will not see any per-transaction surcharges between the headline and the invoice.
Source: provider fee schedule captured August 5 2026.
Speed
Legal and accounting work takes 1 to 2 business days. That covers trustee minutes, the constitution, and ATO paperwork only. The ABN is instant more than 90 percent of the time; otherwise, it can take 1 to 2 months.
Stand-out benefits
- One provider handles deed and accounting with in-house professionals.
- Published asset-complexity tiers make three-year budgeting straightforward.
- Fast paperwork lets you open a bank account and start rollovers earlier than average.
You can explore the full process in SMSF Australia’s setup explainer linked earlier in this guide.
SMSF Warehouse: Best for a detailed published fee schedule
SMSF Warehouse (which trades as Superannuation Warehouse, the name that appears on its audit wording) is ideal if you want every dollar itemised before you sign. Its public PDF lists setup fees, plan tiers, and add-ons, right down to the $30-per-month option for your own Simple Fund 360 login.
- Setup, corporate trustee $1,400 incl. GST; individual trustees $450 incl. GST
- Ongoing service, cash-only fund $70 a month; Advanced share-portfolio plan $110 a month. An independent audit is included in both
Source: SMSF Warehouse fee schedule downloaded August 5 2026.
What to watch
- Every non-standard asset has a price tag: property title searches, crypto reconciliation, brokerage data feeds, and even late-record rework. The costs are published, but you still need to read the full table.
- No published setup SLA and no statement about who drafts or updates the trust deed. If turnaround time or lawyer provenance matters to you, ask before you commit.
Choose SMSF Warehouse when you value line-by-line certainty and are happy to pay precisely for the work your fund needs, nothing more and nothing less.
Xpress Super: Best for bundled bank and broker onboarding
Xpress Super is the convenience pick. The firm sets up your SMSF, registers the company, and opens linked bank and brokerage accounts in a single workflow, so you fill out fewer forms and reach your first trade sooner.
Pricing
- Setup, fund documents $700 plus company registration $1,005 (confirm GST with the provider)
- Annual administration, $1,925 a year, including the independent audit
Source: Xpress Super fee schedule downloaded August 5 2026.
Property, GST, or pension work costs extra, so read the full schedule if those assets are on your radar.
Minimum-balance policy
Xpress recommends at least $200,000 before it will accept a new SMSF. That is a house rule, not an ATO requirement, and the firm may decline lower balances.
Questions to ask before signing
-
Is the quoted setup price inclusive or exclusive of GST?
-
Which accounting platform underpins the client portal?
-
What are the add-on fees for property, crypto, or a pension account?
Choose Xpress Super if you want a bundled start-to-trade package and you’re comfortable meeting its minimum-balance guideline.
Heffron: Best for complex or technically demanding administration
Heffron is the administrator to call when your SMSF holds multiple properties, private loans, crypto wallets, or legacy pensions. A bench of tax lawyers, actuaries, and senior accountants supports both advisers and retail trustees.
Pricing snapshot
- Setup, $550 for the fund establishment service plus $1,007 for the special purpose trustee company, the same on both schedules (GST inclusive).
- Annual administration, Heffron publishes trustee pricing at $3,195 incl. GST for Streamlined, $3,770 for Standard and from $4,375 for Advanced, each figure including the independent audit. The lower adviser rates you may see quoted elsewhere ($2,700 / $3,300 / from $3,930) require five or more funds placed with Heffron through an adviser.
Source: Heffron trustee and adviser administration pricing, retrieved August 5 2026.
Timing
Heffron does not publish a turnaround time for a full establishment. The extra checks complex structures need make the pace slower than a vanilla fund, so ask for a written estimate if you have a settlement date.
Technology
A proprietary online portal feeds directly into Heffron’s administration engine, giving you a real-time tax and compliance dashboard (no mobile app yet).
Choose Heffron if your SMSF looks more like a small-business balance sheet than a vanilla ETF portfolio and you want specialists who have already solved the tricky edge cases.
BlueRock: Best for clear trustee-structure and LRBA setup pricing
BlueRock SMSF Setup and LRBA Pricing Page Screenshot
BlueRock stands out for posting side-by-side prices for individual- and corporate-trustee structures and a dedicated LRBA package, which is rare transparency for property buyers.
|
Item |
Published price (incl. GST) |
Source: BlueRock SMSF setup page, captured August 5 2026 |
|
Individual-trustee setup |
$1,450 |
|
|
Corporate-trustee setup |
$2,750 |
|
|
LRBA loan structure |
$2,100 |
What’s included
Deed drafting (lawyer reviewed), ASIC company registration, ABN/TFN applications, ATO regulated-fund election, bank account guidance, and rollover assistance. BlueRock’s wider advisory arm can also handle property finance or tax structuring if required.
What still needs a quote
- Annual administration and audit fee, which varies by asset mix and transaction volume
- Turnaround time; ask for a written SLA if you have a settlement date
- Accounting platform; marketing mentions dashboards but not the underlying engine
Choose BlueRock if you want upfront clarity on trustee structures or have an LRBA in sight, but lock in the ongoing admin quote before moving the first dollar.
Putting it all together: detailed comparison
Here is the side-by-side snapshot of setup cost, corporate-trustee status, annual admin, audit inclusion, and software, using prices verified on August 5 2026 (after ASIC lifted the company-registration fee to $636 and the annual review to $70).
|
Provider |
Setup fee (corporate trustee) |
ASIC $636 included |
Annual admin (simple assets) |
Audit included |
Accounting platform |
Property add-on |
Crypto add-on |
|
SMSF Australia |
$2,000 + GST |
✔︎ |
from $1,300 + GST |
✔︎ |
Class Super |
Complex-tier flat fee |
Complex-tier flat fee |
|
SMSF Warehouse |
$1,400 incl. GST |
✔︎ |
$1,320 incl. GST |
✔︎ |
Simple Fund 360 (optional login) |
Title-search surcharge |
Per-wallet fee |
|
Xpress Super |
$1,705* |
✔︎ |
$1,925 (GST TBC) |
✔︎ |
N/P |
$515 per property, per year |
Quote |
|
Heffron |
$1,557* |
✔︎ |
from $3,195 incl. GST |
✔︎ |
Heffron portal |
Included |
Included |
|
BlueRock |
$2,750 incl. GST |
✔︎ |
Quote |
TBC |
N/P |
LRBA package $2,100 |
Quote |
*Combined fund-setup and company-registration cost.
Entry-level admin bundles in this comparison range from about $1,300 to more than $3,000 a year for a plain share-and-ETF portfolio. A lower setup price does not always lead to the cheapest three-year total.
Four of the five bundle the audit into the annual fee; BlueRock prices setup only, so its audit arrangement has to be quoted. Even where the audit is included, the engagement model differs. Some firms pay the auditor and fold the fee into your bundle, while others “coordinate” and pass the invoice through. Always confirm who signs the engagement letter, and whether extra audit work attracts a surcharge.
Tech matters too. Class Super and Simple Fund 360 dominate professional SMSF circles, while proprietary portals can lock you into one workflow. Pick the engine your accountant, and any future administrator, already uses.
Up next: corporate- versus individual-trustee pros and cons, realistic timelines, and the red-flag checklist to narrow your shortlist.
Fixed fee versus quote on request
Why fixed fees feel safer
A published fixed fee shows the bill before the work starts, so you can model a three-year budget and dodge the “free-setup, expensive-year-two” trap. The cheapest setup in this guide is not the cheapest fund to run over three years: SMSF Warehouse’s $1,400 establishment comes with $1,320 a year, while Heffron’s $550 establishment comes with $3,195.
Fixed pricing also pushes the provider to streamline its own systems - clean bank feeds, automated coding, and audit-ready workflows - so you receive faster dashboards and fewer record-keeping emails.
Finally, a fixed figure heads off disputes. If property valuations, crypto statements, or actuarial certificates cost extra, the provider must list them in black and white rather than spring an unexpected invoice at tax time. Transparency builds trust, especially when lodgement deadlines loom.
When a quote can still be better
A bespoke quote can work in your favour if your fund will start life with multiple properties, private loans, or legacy pensions. Complex assets rarely fit neatly into a one-price table, and a tailored scope can be cheaper than triggering every “out-of-scope” surcharge in a fixed bundle.
Corporate trustee versus individual trustees
Your choice of trustee structure shapes everything from paperwork to estate planning, so here is the fast, jargon-free rundown.
How a corporate trustee works
- A special-purpose company becomes the legal owner of fund assets.
- Members serve as directors. If someone joins or leaves, you update ASIC records instead of retitling every asset.
- Costs: $636 to register the company and $70 a year for ASIC’s review fee (ASIC rates current for 2026 to 27).
How individual trustees work
- Each member holds assets in their own names.
- When membership changes, every title deed, bank account, and broker record must be redrawn.
- You skip the company fees, yet even one membership change can erase those savings.
Why most advisers favour a company
Regulators prefer the corporate model because a company cannot die or lose capacity, and its members can change without retitling a single asset; the fund keeps running even if a director faces personal issues.
A practical rule of thumb (general information only)
Two-member funds often start with a company and treat the ASIC fees as cheap insurance. Single-member funds that appoint an individual co-trustee frequently switch to a company later - usually after discovering how much retitling costs.
Plan your budget with the company fees in mind, then compare providers on everything else.
How long does online SMSF setup take?
Providers may promise “documents in 24 hours,” yet that covers only the forms they control. The full journey has four checkpoints, each with its own clock:
-
Identity checks and online application, legal and accounting work, including the deed, company constitution, and trustee minutes, takes 1 to 2 business days.
-
ASIC registration, electronic lodgement is quick, but the company number can still take 24 to 48 hours to arrive, longer around public holidays.
-
ATO regulated-fund election, the ABN is instant more than 90 percent of the time; otherwise, it can take 1 to 2 months. The notice of compliance follows a few days later.
-
Bank, broker, and rollovers, your bank account stays blocked until the fund has an ABN, and rollovers wait until Super Fund Lookup lists the fund as Registered.
Because of these dependencies, no provider publishes a total setup time. If you are buying property, build extra time into the contract so the fund exists, cash clears, and trustees are not signing under pressure.
Technology and platform checklist
The accounting engine behind your SMSF determines whether you spend weekends chasing bank statements or sit back while live data updates itself.
1. Core engine
Class Super and BGL Simple Fund 360 hold the largest market share among professional administrators. They pull transactions from banks, brokers, and supported crypto exchanges, auto-coding them to the chart of accounts and cutting audit errors.
2. Dashboard and exports
A solid portal shows daily balances, unrealised gains, pension caps, and contribution limits, then lets you export the full general ledger (CSV or Xero), not screenshots. Proprietary portals can look slick but sometimes trap data. Always request a sample export.
3. Data feeds
Most platforms handle CBA, Macquarie, and major ASX brokers. Feeds get patchy with offshore options trading or smaller crypto exchanges. When a feed is missing, reconciliation drops back to spreadsheets.
4. Security
By 2026 you should expect MFA, separate director logins, and read-only bank connections. If a provider can’t tick those boxes, think twice.
5. Portability
Check whether the software licence moves with you or stays with the administrator. A transferable Class or BGL file lets a new accountant click “accept transfer.” A locked portal forces a messy CSV dump.
Five questions to ask before signing
-
Which accounting engine powers the client portal?
-
Can I export the entire general ledger?
-
Which banks, brokers, and crypto exchanges feed direct data?
-
Is multi-factor authentication compulsory for every trustee login?
-
Will my historical data transfer intact if I change administrator?
Clear answers to these questions will save hours of frustration once the novelty of a new deed wears off.
Audit independence: what “audit included” should mean
Every SMSF must pass an independent audit each financial year. Independent means the auditor cannot also prepare the fund’s accounts, exactly what APES 110 (Code of Ethics for Professional Accountants) and the ATO’s auditor independence guidance both require.
When you read “audit included,” ask two questions:
-
Who signs the audit report?
-
Who pays that person?
Compliant model
The administrator outsources the review to a registered SMSF auditor who has no role in coding transactions or drafting the tax return. The auditor invoices the administrator, and the administrator folds that fee into your annual package. You still fund the cost, yet the engagement letter and work papers sit with a separate professional, preserving independence and cutting the risk of an ATO penalty.
“Audit coordinated” grey zone
Here, the administrator finds an auditor, yet you pay the invoice directly. Coordination isn’t wrong, but it can turn a “$1,500 all-in” service into about $2,000 once the second bill arrives. Always request a written quote from the auditor before assuming the total cost.
Red flags
- The same ABN appears on both the admin invoice and the audit engagement.
- The audit fee flexes with your investment performance, rather than work performed.
- The provider refuses to name the auditor in writing.
Independent audits are your fund’s annual health check - make sure the surgeon isn’t also writing the pathology report.
Regulatory developments every SMSF setup provider must track
Rules can change faster than marketing copy. Two big 2026 shifts affect every new fund.
1. ASIC fee indexation - effective 1 July 2026
- Company registration for a special-purpose corporate trustee: $636 (was $611).
- Annual review fee: $70.
If a provider still quotes $611, you will pay the $25 shortfall when ASIC issues the invoice. Accurate statutory fees act as an easy credibility test; out-of-date numbers signal deeper compliance gaps.
2. AML/CTF reforms - accountants and lawyers now “reporting entities”
From 1 July 2026 accountants and lawyers who establish SMSFs must verify identities, flag suspicious transactions, and keep detailed records under the expanded AML/CTF regime administered by AUSTRAC.
For trustees that means:
- Certified ID and proof-of-address for every member, along with director IDs for corporate trustees.
- Questions about the source of rollover funds and the investment plan.
- Possible delays if documents are missing or handwritten forms remain in use.
Ask each provider:
- Which digital-ID tool do you use?
- How long does approval usually take?
- Will the stored data streamline future bank or broker onboarding?
Extra questions are here to stay, so partner with a service that treats AML as a system rather than a last-minute scramble.
Can you run an Australian SMSF while living in New Zealand?
Short answer: sometimes - but tread carefully.
The Australian residency test
An SMSF keeps its tax concessions only if it remains an Australian superannuation fund. That status hangs on three pillars:
- Established in Australia.
- Central management and control (CM&C) ordinarily in Australia. The ATO accepts a temporary absence of up to two years without breaking residency.
- Active-member rule. The fund passes if it has no active members, or if Australian-resident active members hold at least 50 percent of the market value of the fund assets attributable to active members’ interests. Note this is measured on assets, not on who is contributing: stopping contributions does not fix a residency problem.
Typical scenarios
- Contract under two years, the ATO treats this as a temporary absence and the fund usually stays compliant.
- More than two years overseas, CM&C shifts offshore unless at least half the directors or trustees remain Australian residents. Flying back for a meeting will not fix it.
- Starting a brand-new fund from NZ, ask each provider directly whether it will establish a fund where no member is an Australian resident, and ask the bank the same question about the account. Neither answer is safe to assume, and both are easier to get before you pay a setup fee than after.
Practical hurdles
- KiwiSaver cannot be moved into an SMSF. The Trans-Tasman Retirement Savings Portability Scheme allows transfers only between a KiwiSaver scheme and a complying APRA-regulated Australian super fund. SMSFs are regulated by the ATO, not APRA, so they sit outside the scheme. If you want your KiwiSaver balance in Australia, it has to land in an APRA-regulated fund first, and only a small number of those accept KiwiSaver transfers. Transfers must also be of the whole balance; partial transfers are not allowed.
- Banking & SuperStream, the fund still needs an AUD bank account and an electronic service address; foreign accounts cannot receive employer contributions.
- AML checks, opening Australian accounts from overseas means extra ID certification and delays.
- NZ tax, New Zealand taxes residents on worldwide income under Inland Revenue’s worldwide income rule, so SMSF earnings may be taxable there unless double-tax relief applies.
What usually works
- Offshore for fewer than two years: keep the SMSF, but ensure decisions are still made in Australia.
- Offshore for more than two years: either appoint a professional Australian trustee company with real control, or pause the SMSF idea until you return.
- Already overseas long term: consider rolling back to an Australian retail or industry fund before leaving; the penalty tax for a non-resident SMSF can dwarf any admin savings.
General information only. Cross-border residency rules are unforgiving, so seek advice from professionals licensed in both Australia and New Zealand before lodging paperwork.
Conclusion: Red flags when comparing SMSF setup providers
Choosing a provider is half spreadsheet, half common sense. Watch for these red flags and pause for written clarification if you spot one.
- Out-of-date ASIC fee. Company registration is $636 from 1 July 2026. A page quoting $611 is already behind on compliance.
- “Free setup” with no footnote. Legit offers spell out the catch, usually an annual-admin lock-in or a separate company fee.
- No GST label. A quote that reads $1,500 could swing ten percent either way. Look for “inc GST” or “+ GST” on every line.
- Anonymous trust deed. A deed generated by software but unsigned by an Australian lawyer can cost thousands to fix when you need to borrow or add members.
- Vague audit wording. “Audit arranged” often means a second invoice. Look for “independent audit included” and a named, external SMSF auditor.
- Mandatory investment tie-ins. A provider that forces one broker or branded bank account limits your flexibility, clouding fee comparisons.
If the answers to these checks feel slippery, keep shopping; a transparent administrator will welcome the scrutiny.